

By Elizabeth Walker on October 30, 2026 at 10:00 AM
If you’re choosing your company’s employee benefits and considering a new health insurance option, your organization's contribution strategy is a key factor in that decision. When you factor the new benefit’s cost into your budget, you need to know how much employees will contribute to health coverage and what percentage you’ll pay.
With traditional group health coverage, employers typically contribute a set percentage toward the plan’s premium, and employees pay the remainder, usually through a pre-tax payroll deduction. So, what percentage of health insurance premiums do employers typically pay in the United States?
In this blog post, you’ll learn:
- How much employers typically contribute toward employees’ health insurance premiums, and how those costs differ for self-only and family coverage.
- What factors influence group health insurance costs for both employers and employees.
- How health reimbursement arrangements (HRAs) can help employers manage cost pressures, set predictable budgets, and give employees more control over their healthcare.
How much does group health insurance cost?
When a business provides health coverage to employees, it typically has two primary options. An employer can purchase a plan (or plans) from a commercial insurance carrier to cover all eligible employees and their qualified dependents. Most people know these plans as traditional group health plans or “fully-insured plans.”
There are also self-funded health plans. With that type of health insurance, employers pay employee medical claims directly. They may also use a commercial carrier or third-party administrator to manage the plan.
According to KFF’s 2026 Employer Health Benefits Survey, the average cost of group coverage in 2026 was $9,804 annually (or $817/month) for self-only plans and $28,303 annually (or $2,359/month) for family policies1. Although these numbers can vary by insurer, policy type, and ZIP code, employers will know their annual rate when they buy a new plan or renew their current policy. KFF includes an average of fully-insured premiums and the cost of a former employee with a self-funded plan to enroll in COBRA in its calculations.
What percent of health insurance is paid by employers?
According to KFF, in 2026, employers covered 82% of employees’ single-coverage plans and 73% of employees’ family insurance plans on average2.
The following chart provides a closer look at these percentages:
|
Employer percentage |
Employer dollar amount |
Employee percentage |
Employee dollar amount |
|
|
Self-only premium of $9,804 annually |
82% |
$8,132 annually |
18% |
$1,672 annually |
|
Family premium of $28,303 annually |
73% |
$20,833 annually |
27% |
$7,471 annually |
Large employer contributions vs. small employer contributions
The amount employers pay on average also depends on the size of the organization.
According to KFF, below are the numbers for self-only coverage by company size3:
|
Employer percentage paid of self-only premium |
Employer dollar amount |
Employee percentage paid of self-only premium |
Employee dollar amount |
|
|
Small to mid-sized employers with 10-199 employees |
85% |
$8,143/annually |
15% |
$1,451/annually |
|
Large employers with 200 or more employees |
82% |
$8,128/annually |
18% |
$1,736/annually |
In contrast, here is the data for family plans by company size4:
|
Employer percentage paid of entire self-only premium |
Employer dollar amount |
Employee percentage paid of entire self-only premium |
Employee dollar amount |
|
|
Small to mid-sized employers with 10-199 employees |
65% |
$17,601/annually |
35% |
$9,687/annually |
|
Large employers with 200 or more employees |
76% |
$21,752/annually |
24% |
$6,840/annually |
While large employers typically contribute a significant amount to employees’ healthcare, small employers sometimes cover even more. According to KFF, employers pay the full self-only premium for 29% of enrolled employees at small- to mid-sized organizations, compared with only 5% of workers in large companies. For family plans, employers pay the full premium for 9% of covered employees at small businesses, compared to 2% at large organizations.
One possible reason is that small businesses have fewer eligible workers. That can make it easier for them to pay the full premium for their employees — whether self-only or family coverage — than for large businesses with significantly more employees.
What percentage of businesses offer health benefits?
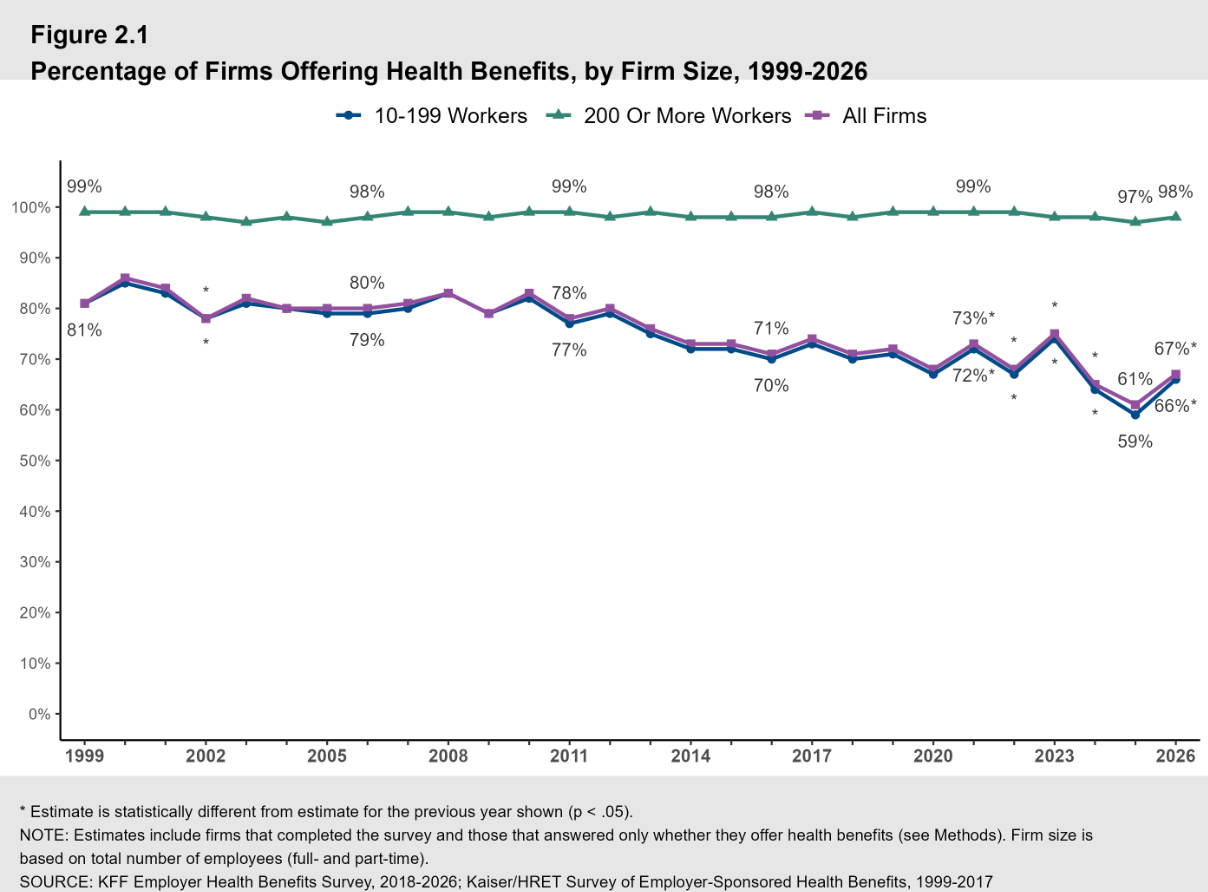
While virtually all organizations with 1,000 or more workers offer health coverage to employees, small employers are different. Only 59% of businesses with ten to 24 workers offered coverage to their employees in 20265. While this is up from 51% in 2025, 41% of small employers are still forgoing health insurance coverage.
Small employers generally have tighter budgets, but rising health insurance costs can make it even harder to offer the benefit. The annual premium for family coverage has increased 26% over the last five years and 47% over the previous 10 years, far more than workers’ wages or inflation.
This increase in healthcare services and costs can make it challenging for employers to continue offering a health benefits program that provides enough value.
How much does group health insurance cost for employees?
From the type of plan you choose to your employees’ health conditions, many factors affect how much your employees will pay for health insurance.
Looking again at KFF’s 2026 report, employee contributions toward a family plan were $7,471 annually (reported as 27% of the average premium) and $1,672 (reported as 18%) for single coverage.
The premium cost of a group health insurance plan typically increases each year. You can adjust contribution strategies, health plan types, or covered benefits each year to reduce premium fluctuations and control health insurance costs.
How can employers better control group health insurance costs?
Although your health insurance program is likely one of the most expensive benefits you’ll offer at your organization, it’s an essential investment in your company’s future. By better understanding the factors that affect your employee health benefits costs, you’ll gain greater cost control over your budget and set your workers up for success.
The annual cost of providing group insurance to employees depends on the following key factors:
- The health insurance company
- The plan type. Common policies are preferred provider organizations (PPOs), exclusive provider organizations (EPOs), point of service plans (POSs), and health maintenance organizations (HMOs).
- The provider network
- The plan’s features and cost-sharing amounts. This includes annual deductibles, copayments, coinsurance rates, and out-of-pocket maximums.
- Your ZIP code
- Your employer contribution amount.
- To keep health insurance costs low for your company, you can shift more of the cost burden to your employees. But keep in mind that moving too much of the cost to your staff can negatively impact employee well-being.
- Your employees' demographics or plan rates for the “risk pool” at your company.
- For example, older workforces tend to have higher medical care costs, which might increase your group’s overall rates.
Alternative health benefit options for employers
If you’re struggling to meet minimum contribution requirements, alternative health benefit options can be helpful. For example, instead of paying for employer-sponsored plans through an insurer, you can use a stand-alone health reimbursement arrangement (HRA). This type of health benefit lets employers give employees a set amount of tax-free money, which they can use to pay for individual health plan premiums and other qualified out-of-pocket costs.
Because employers can set their own contribution limit, many find HRAs more predictable and affordable than traditional health benefit options. In many states and counties, individual health insurance premiums are cheaper than small group premiums, so you can save more by reimbursing your employees’ premiums through an HRA.
The following four simple steps outline how an HRA works:
- You choose a monthly allowance that your employees can use on premiums, medical services, and healthcare items. You can also limit contributions to premiums only if you choose.
- Employees buy their own health insurance plan on a private exchange, the federal Health Insurance Marketplace, or a state-based exchange. They can choose any qualifying medical policy that fits their budget and needs, including their preferred insurer and provider network.
- Employees pay their monthly premiums and other out-of-pocket medical costs upfront.
- Once they provide proof of purchase for an eligible expense, you reimburse them up to their set allowance limit. HRA reimbursements are income-tax-free for employees. They’re also tax-deductible and free of payroll taxes for employers.
Below, we’ll go over two stand-alone HRAs for employers who choose not to offer a group health coverage plan.
Qualified small employer HRA (QSEHRA)
A qualified small employer HRA (QSEHRA) is for businesses with fewer than 50 full-time equivalent employees (FTEs) that don’t offer a traditional group or ancillary plan. With a QSEHRA, you can reimburse employees for individual insurance premiums and qualified out-of-pocket medical expenses. To use the benefit, employees enroll in a health plan that provides minimum essential coverage (MEC). This can include coverage through a spouse’s or parent’s group health plan.
The IRS sets annual caps on how much employers can contribute through a QSEHRA, but you can contribute up to that limit. You also decide whether the benefit will reimburse premiums only or both premiums and qualified medical expenses.
You must offer the QSEHRA to all your full-time W-2 employees. However, you may include part-time staff as long as they receive the same monthly allowance as your full-time workers.
Check out our latest QSEHRA annual report to see how a QSEHRA helped our customers.
CHOICE Arrangements
A CHOICE Arrangement, formerly known as an individual coverage HRA (ICHRA), also reimburses employees for qualifying individual insurance premiums and eligible medical expenses. However, it offers more flexibility for employers than a QSEHRA. Employers of any size can adopt an ICHRA, and the IRS imposes no limits on contribution amounts. You can customize eligibility and allowance levels across 11 employee classes and may also vary amounts by age or family size.
Applicable large employers (ALEs) may also use a CHOICE Arrangement instead of group coverage to meet the Affordable Care Act’s employer mandate, as long as they offer it to at least 95% of full-time employees and their dependents, and the allowance meets federal affordability standards.
Remodel Health and PeopleKeep customers offered an average monthly ICHRA contribution of $591 for single employees in 2026. This comes to an average of $7,092 annually. This is less than the average self-only employer health insurance contribution of $8,132 annually that KFF found in their report.
Conclusion
When considering how much employer-sponsored health plans will cost your company, you must consider what percentage of health insurance premiums they’ll cover. Many larger companies that offer traditional employer-sponsored health insurance pay for most of their employees’ monthly premiums. However, small businesses may not have the benefits budget to cover a significant portion of group plan premiums.
Many employers prefer stand-alone HRAs because they’re more flexible and let employees choose their own plans. If an HRA sounds like a good choice for your company, PeopleKeep by Remodel Health can help! Schedule a call with us today to learn more about which HRA is right for you.
This article was originally published on August 12, 2020. It was last updated on October 30, 2026.
References
1. KFF 2026 Employer Health Benefits Survey
2. KFF 2026 Employer Health Benefits Survey: Worker and Employer Contributions for Premiums
3. KFF 2026 Employer Health Benefits Survey: Figure 6.7
4. KFF 2026 Employer Health Benefits Survey: Figure 6.8
5. KFF 2026 Employer Benefits Survey: Health Benefits Offer Rates

How much do employers pay for health insurance?
In this blog, we’ll break down the average cost of health insurance per employee as well as the average cost of employer-provided group health insurance.
What is an administrative services only (ASO) benefit plan?
Learn what an administrative services only (ASO) benefit plan is and how it allows businesses to self-fund employee benefits with third-party support.
HRAs and W-2 annual reporting
Learn about HRA W-2 annual reporting requirements. Understand what employers need to include on employees' W-2 forms for HRA compliance.